Greek Capital Tankers adopts balloon financing for 11 VLCCs ギリシャのキャピタル・タンカーズ、VLCC11隻にバルーン返済方式採用
$930.3m financing package leaves up to 75% of loan principal repayable at maturity, highlighting benefits and risks for shipowners
総額9.3億ドル、元本の最大75%を満期時に一括返済、船主のメリットとリスク
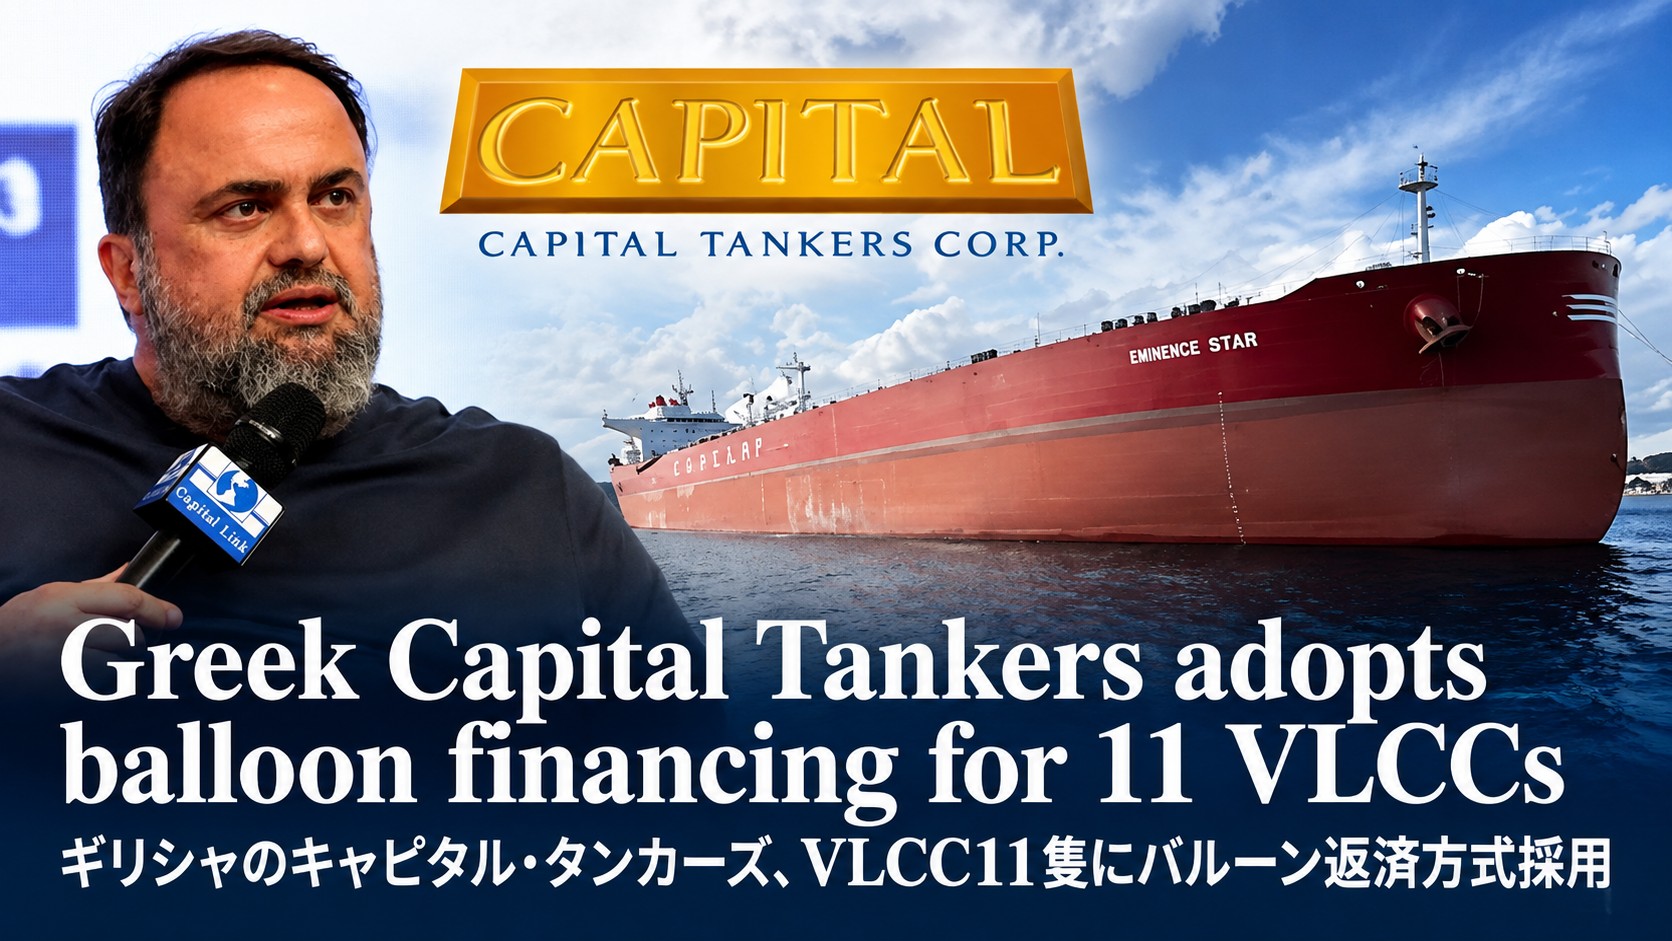
Capital Tankers, the Greek shipowner backed by Evangelos Marinakis, has signed financing agreements totalling $930.3m for 11 very large crude carriers (VLCCs) under construction in China and South Korea. The agreements adopt balloon repayment structures under which approximately 50% of the original loan principal for eight Chinese-built vessels and 75% for three South Korean-built vessels will be repaid in lump sums at maturity.
The arrangements also provide a useful case study for Japanese shipowners and financial institutions when assessing ship financing structures and repayment risks.
■ What you can read in the full article (approximately 2,000 Japanese characters)
→ A $930.3m financing package for 11 VLCCs: what lies behind the Greek shipowner’s decision to adopt balloon repayments?
→ Financing for Chinese-built vessels requires approximately 50% of principal to be repaid at maturity, compared with 75% for South Korean-built ships. What explains the difference in terms?
→ Lower principal repayments during vessel operations help preserve funds for investment, but what are the benefits and potential risks for shipowners?
→ Vessel values in five and ten years will influence repayment capacity. How do VLCC market conditions and refinancing risks interact?
→ Implications for Japanese shipowners’ bank financing and JOLCO structures: how balloon repayments could expand ship investment opportunities.
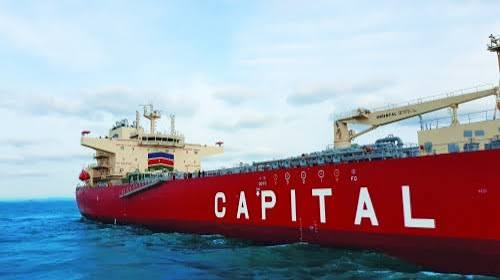
Photo courtesy of Capital Link
(The remainder of the article is available to paid subscribers in English and Japanese. The Japanese-language version follows the English article.)
ギリシャのキャピタル・タンカーズ、VLCC11隻の融資にバルーン返済方式を採用
総額9.3億ドル、元本の最大75%を満期時に一括返済、船主のメリットとリスク
ギリシャの有力船主エヴァンゲロス・マリナキス氏が率いるキャピタル・タンカーズ(Capital Tankers)は、中国と韓国で建造するVLCC(超大型原油タンカー)11隻を対象に、総額9億3030万ドルの融資契約を締結した。注目されるのは、中国建造船8隻では融資元本の約50%、韓国建造船3隻では約75%を満期時に一括返済するバルーン返済方式だ。
日本の船主や金融機関にとっても、船舶投資の資金調達と返済リスクを考えるうえで参考となる事例だ。
■記事本文では以下の内容を読むことができます(記事全文約2,000文字)
→ VLCC11隻に9.3億ドルの巨額融資、ギリシャ船主が選んだバルーン返済の狙いとは。
→ 中国建造船は元本の約50%、韓国建造船は約75%を満期に返済、その条件の違いに注目。
→ 運航中の返済負担を軽減し投資余力を確保、船主にとってのメリットと潜在的なリスク。
→ 5年後、10年後の船価が返済能力を左右、VLCC市況と借り換えリスクの関係を読み解く。
→ 日本船主の銀行融資やJOLCOにも示唆、バルーン返済が広げる船舶投資の可能性。
(続きは英語と日本語で書かれた有料版の本文でお読みください。日本語の記事は英文記事に続いて掲載されています)
関連記事
-
 〆 Inside Report Diverging Views Over New Fuels, MOL’s Hashimoto responds to Maersk「LNG燃料への課金」は是か非か
-
〆 Inside Report: Why USTR’s New Tariffs Target All Car Carriers Worldwide USTR、全世界の海運会社のPCTC対象の「なぜ」
-
〆 Union Maritime Hosts Second Anniversary Reception in Tokyo:英ユニオンマリタイムが日本事務所設立2周年記念パーティーを開催。
-
〆 Clarksons Japan Hosts Spring BBQ for Japanese Maritime Stakeholders:クラークソンズ、日本の海事関係者を招きBBQ開催
-
〆Osaka Gas makes first LNG bunkering to MOL’s dedicated iron ore carrier — 大阪ガス、商船三井のLNG燃料鉄鋼原料船に初供給
-
〆INSIDE REPORT: Imabari Shipbuilding sees 2,134 Training Program plans revoked. 技能実習法違反、今治造船だけの問題か。
-
〆 INSIDE REPORT TSUNEISHI Block Loading the Compay’s First Methanol-Fuelled Ship 常石造船、初のメタノール燃料船を建造
-
〆 Inside Report An Exodus from Japan’s Trading Houses’ Shipping Divisions: “止まらない日本の商社船舶部の人材流出