NS United Kaiun Kaisha raises full-year net income forecast to ¥26.4bn NSユナイテッド海運、連結純利益264億円に上方修正
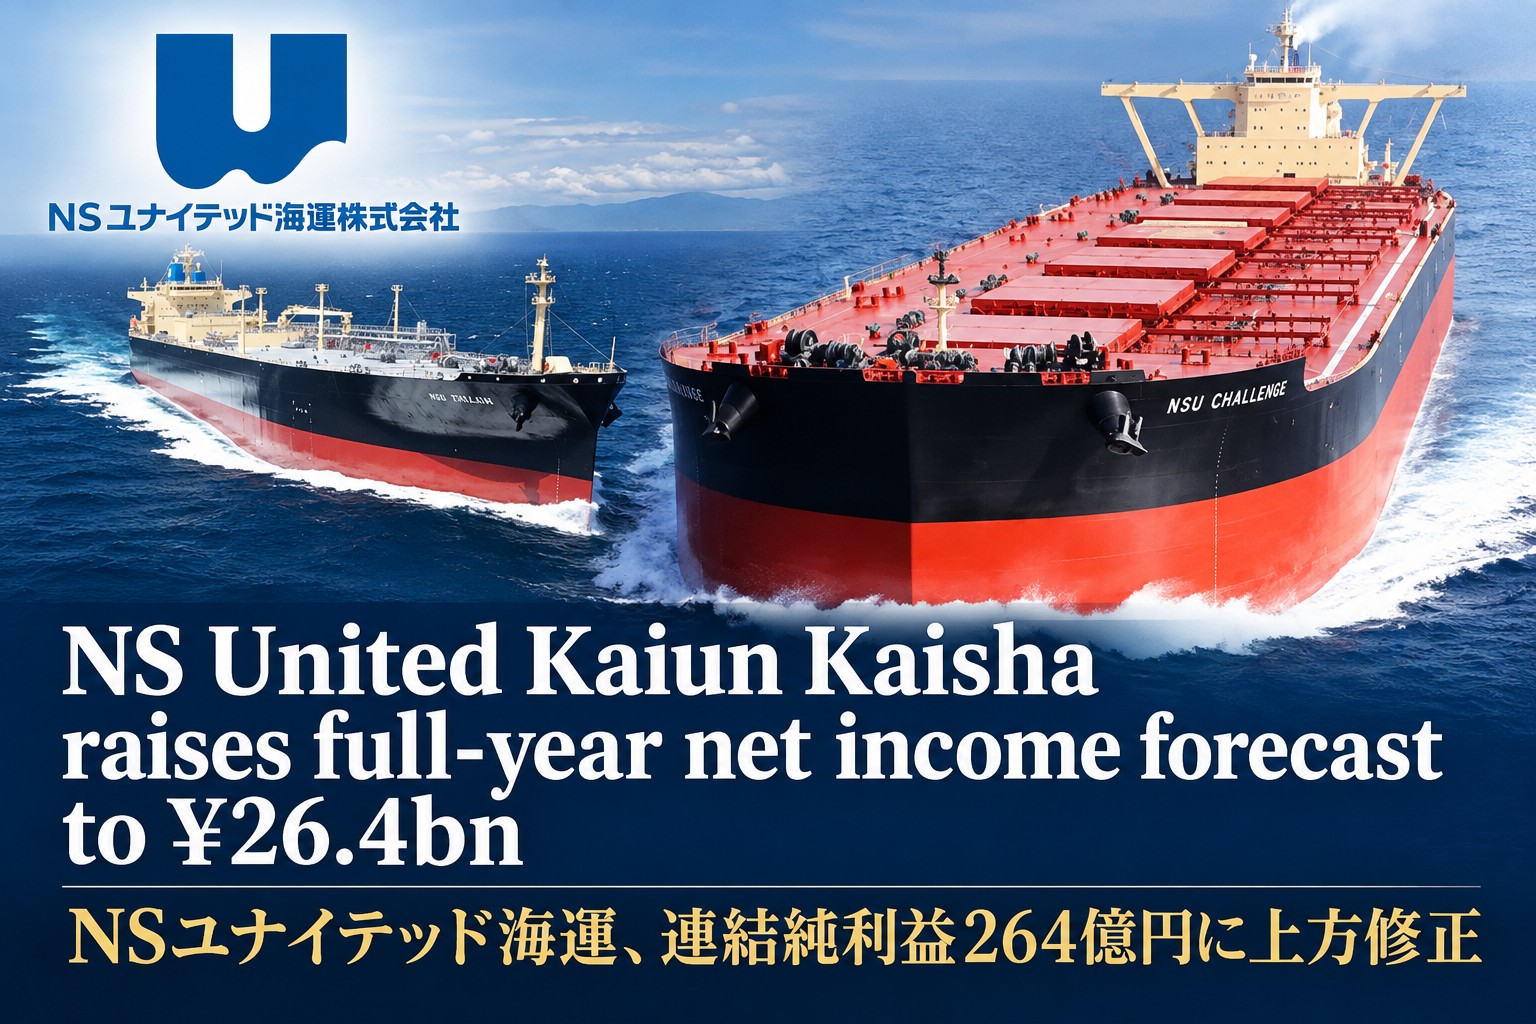
Strong dry bulk and VLGC markets lift earnings, with ROE of 14.7% at a high level among major shipping companies
ドライ・VLGCが収益押し上げ、ROE14.7%で主要海運の高水準へ
NS United Kaiun Kaisha announced on 30 October that its interim results for the financial year ending March 2027 showed substantial increases in both revenue and profit, supported by strong market conditions in the international dry bulk and VLGC (very large gas carrier) sectors.
The company raised its full-year consolidated net income forecast from ¥25bn to ¥26.4bn. Return on equity (ROE) is projected to reach 14.7%, indicating a high level of capital efficiency among major international shipping companies.
■ What you can read in the full article (approximately 2,000 Japanese characters)
→ NS United raises its net income forecast to ¥26.4bn, as strong dry bulk and VLGC markets drive earnings growth.
→ Operating income is projected to rise 57% year on year to ¥32.2bn. What is driving profitability towards record levels?
→ ROE is forecast at 14.7%, exceeding 10% for the sixth consecutive year and highlighting high capital efficiency among major shipping companies.
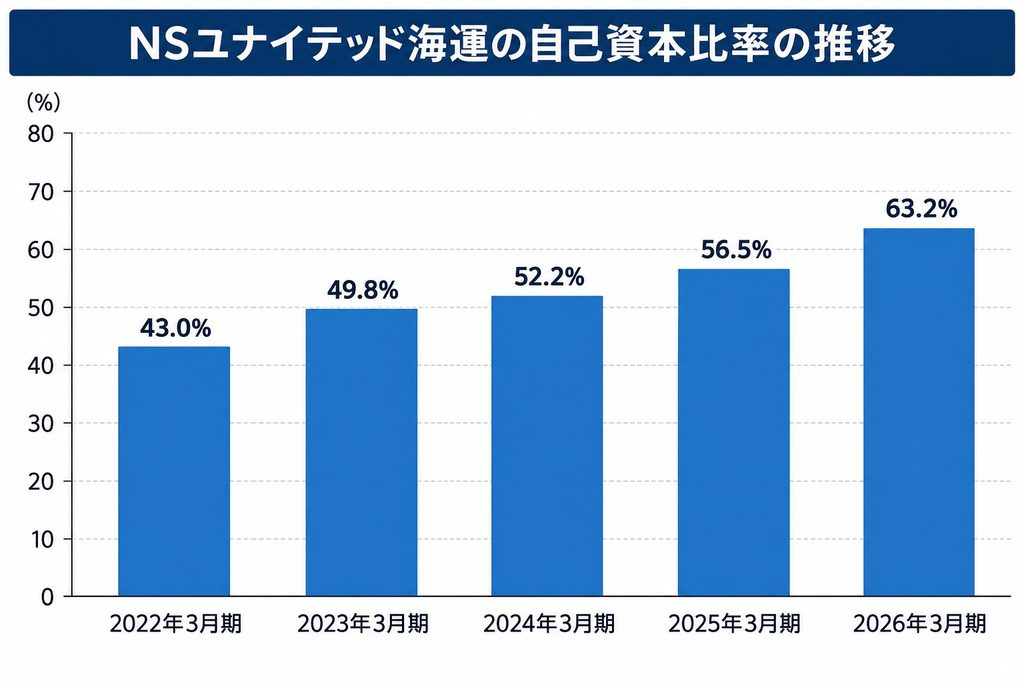
→ The equity ratio has climbed steadily from 43.0% to 63.2% over five years, reflecting a strengthening financial position.
→ Despite strong earnings, no dividend is planned for this financial year. What NYK’s proposed takeover bid means for the company and the possibility of delisting.
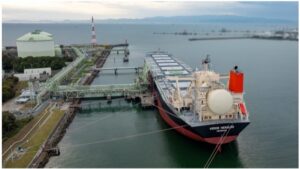
Photo courtesy of NS United Kaiun
(Please read the full article in the paid edition, available in both English and Japanese. The Japanese version follows the English article.)
NSユナイテッド海運、連結純利益264億円に上方修正
ドライ・VLGCが収益押し上げ、ROE14.7%で主要海運の高水準へ
NSユナイテッド海運が10月30日発表した2027年3月期中間決算は、外航ドライバルク船とVLGC(大型LPG運搬船)の好調な市況を背景に大幅な増収増益となった。
同社は通期の連結純利益予想を従来の250億円から264億円に上方修正した。自己資本利益率(ROE)は14.7%を見込み、主要外航海運会社の中でも高い水準となる見通しだ。
■記事本文では以下の内容を読むことができます(記事全文約2,000文字)
→ NSユナイテッド、純利益264億円へ上方修正。好調なドライ・VLGC市況が収益を押し上げる
→ 営業利益は前期比57%増の322億円へ。過去最高益に迫る収益力の背景とは
→ ROE14.7%、6期連続で10%超へ。主要海運でも際立つ高い資本効率
→ 自己資本比率は5年間で43.0%から63.2%へ。着実に強化された財務基盤
→ 好業績でも今期は無配。日本郵船のTOB計画と上場廃止の可能性を読み解く
Photo courtesy of NS United Kaiun
(続きは英語と日本語で書かれた有料版の本文でお読みください。日本語の記事は英文記事に続いて掲載されています)
- NYK raises FY2026 net income forecast to ¥330bn 日本郵船、2027年3月期純利益を3300億円に上方修正
- MOL names world's first three ammonia-fuelled Capesize bulkers 商船三井、世界初のアンモニア燃料ケープサイズ3隻を共同命名
関連記事
-
 〆 Inside Report Diverging Views Over New Fuels, MOL’s Hashimoto responds to Maersk「LNG燃料への課金」は是か非か
-
〆 Inside Report: Why USTR’s New Tariffs Target All Car Carriers Worldwide USTR、全世界の海運会社のPCTC対象の「なぜ」
-
〆 Union Maritime Hosts Second Anniversary Reception in Tokyo:英ユニオンマリタイムが日本事務所設立2周年記念パーティーを開催。
-
〆 Clarksons Japan Hosts Spring BBQ for Japanese Maritime Stakeholders:クラークソンズ、日本の海事関係者を招きBBQ開催
-
〆Osaka Gas makes first LNG bunkering to MOL’s dedicated iron ore carrier — 大阪ガス、商船三井のLNG燃料鉄鋼原料船に初供給
-
〆INSIDE REPORT: Imabari Shipbuilding sees 2,134 Training Program plans revoked. 技能実習法違反、今治造船だけの問題か。
-
〆 INSIDE REPORT TSUNEISHI Block Loading the Compay’s First Methanol-Fuelled Ship 常石造船、初のメタノール燃料船を建造
-
〆 Inside Report An Exodus from Japan’s Trading Houses’ Shipping Divisions: “止まらない日本の商社船舶部の人材流出