J.P. Morgan sees tanker capacity tight despite easing risks JPモルガン分析、地政学リスク緩和後も船腹逼迫か
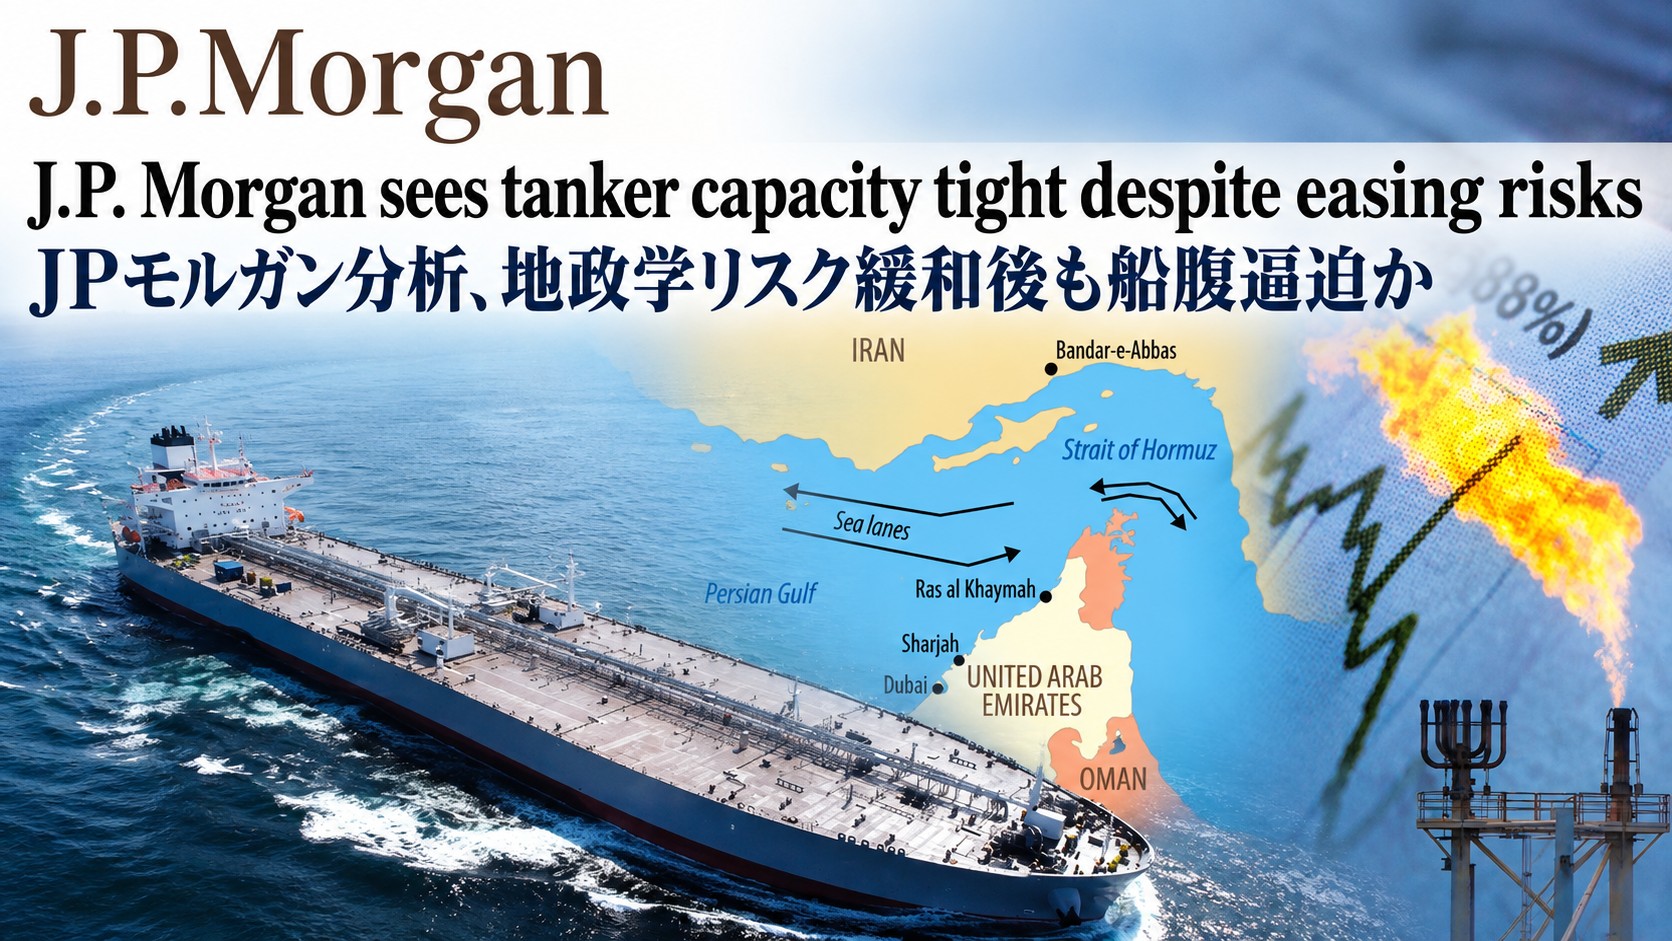
Recovering crude shipments boost VLCC demand, with pressure spreading to Suezmax and Aframax tankers
原油輸送回復でVLCC需要拡大、スエズマックス・アフラマックスにも波及
As crude oil shipments from the Middle East recover, the global tanker market is facing tightening vessel availability. According to an oil market analysis published by US financial group J.P. Morgan on 9 October, the main constraint facing the crude oil market is shifting from a shortage of supply to a shortage of effective transportation capacity.
Longer voyages and reduced operational efficiency associated with Ship-to-Ship (STS) transfers are tying up tanker capacity, with the shortage of VLCCs spreading to Suezmax and Aframax vessels.
■What you can read in the full article (approximately 2,000 Japanese characters)
→ Could tanker capacity remain tight even as geopolitical risks ease? J.P. Morgan identifies a new supply-demand structure.
→ Middle East crude shipments require 35 additional VLCCs. Recovering oil flows create an unexpected shortage of tanker capacity.
→ The VLCC shortage spreads globally, putting upward pressure on Suezmax and Aframax freight rates.
→ VLCC freight rate assessment for US crude shipments to China reaches $80m, dramatically changing the economics of long-haul transport.
→ New earnings opportunities emerge for Japanese shipowners. How should tanker markets be assessed as geopolitical risks ease?
(Continue reading the full article in the paid edition, available in English and Japanese. The Japanese article follows the English version.)
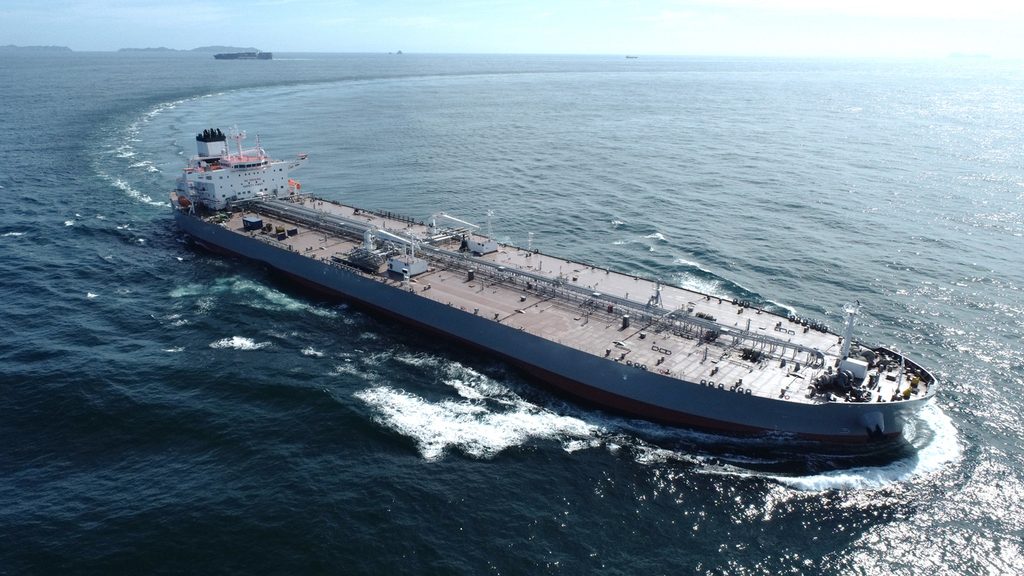
地政学リスク緩和後もタンカー船腹逼迫か JPモルガン分析が示す需給構造
原油輸送回復でVLCC需要拡大、スエズマックス・アフラマックスにも波及
中東からの原油輸送が回復する一方、世界のタンカー船腹需給が逼迫している。米金融大手JPモルガンの10月9日付石油市場分析によると、原油市場の制約要因は供給不足から実効輸送能力の不足へ移りつつある。
航海距離の長期化やShip-to-Ship(STS)移送に伴う運航効率の低下が船腹を拘束し、VLCCの不足がスエズマックスやアフラマックスにも波及している。
■記事本文では以下の内容を読むことができます(記事全文約2,000文字)
→ 地政学リスクが緩和しても船腹逼迫は続くのか。JPモルガンが示す新たな需給構造。
→ 中東原油輸送にVLCC35隻の追加船腹。原油輸送回復が生む意外な船腹不足。
→ VLCC不足が世界に波及。スエズマックス、アフラマックスにも広がる運賃上昇圧力。
→ 米国産原油の中国向けVLCC輸送費が8,000万ドルに。長距離輸送の採算に激変。
→ 日本船主に広がる収益機会。地政学リスク緩和後のタンカー市況をどう読むか。
(続きは英語と日本語で書かれた有料版の本文でお読みください。日本語の記事は英文記事に続いて掲載されています)
- HD Hyundai Marine Solution to buy Goltens for $250m 韓国HD現代マリンソリューション、船舶修繕大手ゴルテンズを2.5億ドルで買収へ
- Container ship sinks in Strait of Hormuz, another vessel struck ホルムズ海峡でコンテナ船沈没、別の1隻も被弾
関連記事
-
 〆 Inside Report Diverging Views Over New Fuels, MOL’s Hashimoto responds to Maersk「LNG燃料への課金」は是か非か
-
〆 Inside Report: Why USTR’s New Tariffs Target All Car Carriers Worldwide USTR、全世界の海運会社のPCTC対象の「なぜ」
-
〆 Union Maritime Hosts Second Anniversary Reception in Tokyo:英ユニオンマリタイムが日本事務所設立2周年記念パーティーを開催。
-
〆 Clarksons Japan Hosts Spring BBQ for Japanese Maritime Stakeholders:クラークソンズ、日本の海事関係者を招きBBQ開催
-
〆Osaka Gas makes first LNG bunkering to MOL’s dedicated iron ore carrier — 大阪ガス、商船三井のLNG燃料鉄鋼原料船に初供給
-
〆INSIDE REPORT: Imabari Shipbuilding sees 2,134 Training Program plans revoked. 技能実習法違反、今治造船だけの問題か。
-
〆 INSIDE REPORT TSUNEISHI Block Loading the Compay’s First Methanol-Fuelled Ship 常石造船、初のメタノール燃料船を建造
-
〆 Inside Report An Exodus from Japan’s Trading Houses’ Shipping Divisions: “止まらない日本の商社船舶部の人材流出